If you’ve been exploring Rollovers as Business Startups (ROBS) as a way to fund your business, you’ve probably come across this question early – how much of my 401(k) can I actually use?
For many aspiring entrepreneurs, the answer is more flexible than they expect.
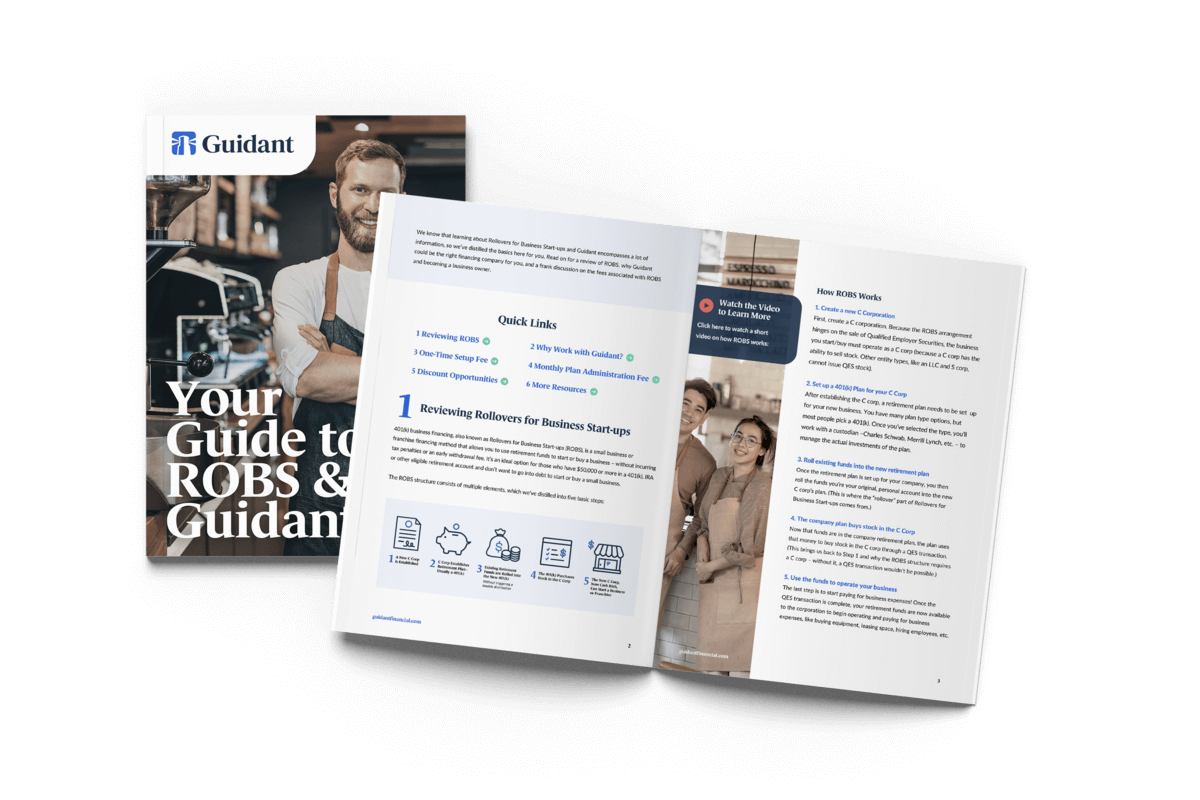
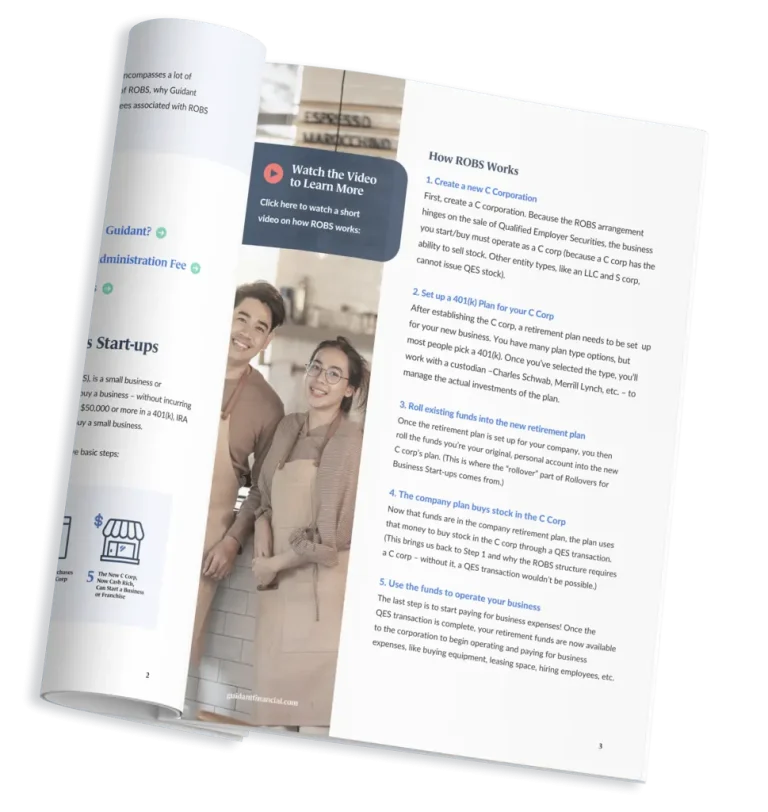
ROBS, also known as 401(k) Business Financing, allows eligible retirement funds to be rolled into a new retirement plan that invests in your business. When properly structured, this gives you access to business capital without treating the transaction as an early retirement withdrawal.
If you’re new to the concept, start with our 401(k) Business Financing Guide for an overview of how the process works.
Is There a Limit on How Much You Can Use for ROBS?
Unlike a 401(k) loan, ROBS does not have a set dollar borrowing limit because ROBS isn’t a loan.
Depending on the retirement funds you have available and their eligibility for rollover, you may be able to use a portion of your eligible retirement savings or roll over the full eligible balance.
That flexibility is one of the key differences between ROBS and traditional business financing.
With an SBA or traditional business loan, the amount you can borrow may depend on factors such as creditworthiness, available collateral, business financials, and lender requirements. With ROBS, you’re investing eligible retirement assets you’ve already accumulated rather than borrowing the money.
However, not every retirement account is immediately available for a rollover. For example, funds held in a current employer’s retirement plan may be subject to the terms of that plan and restrictions on in-service distributions.
You can learn more about the IRS also provides information about ROBS arrangements and their compliance requirements.
Just Because You Can Use More Doesn’t Mean You Should
The real question isn’t just how much you can access, but how much is right for you and your business.
Using ROBS means investing retirement assets in your company. Like any investment, that comes with risk. If the business struggles or fails, some or all of the retirement funds invested in the company could be lost.
That’s why deciding how much to roll over deserves careful consideration.
A ROBS arrangement also creates an employer-sponsored retirement plan subject to ongoing compliance responsibilities. The U.S. Department of Labor explains that retirement plan fiduciaries have responsibilities that include acting prudently, following plan documents, managing plan assets appropriately, and acting in the interests of plan participants and beneficiaries.
The IRS has also identified areas where improperly operated ROBS arrangements can run into compliance problems, including plan administration, stock valuation, prohibited discrimination, and required filings.
If you’re weighing the risks of putting retirement savings into a business, read our guide on the pros and cons of using ROBS.
Three Questions to Ask Before Deciding How Much to Use
Owning a business is very different from investing in a traditional retirement account. While stocks and mutual funds are generally hands-off investments, running a business requires active involvement, including your time, leadership, and decision-making. Before deciding how much of your retirement savings to invest, ask yourself these three important questions.
1. Is Your Business Viable?
Start with the fundamentals. Do you have a solid business plan? Have you researched customer demand, assessed the competition, and mapped out realistic startup costs and financial projections?
Market research and competitive analysis can help you validate your idea, understand your target audience, and identify opportunities to stand out.
It’s also important to confirm that your business can qualify for ROBS. Since a ROBS arrangement involves a retirement plan purchasing employer stock, the business must be structured as a C corporation.
2. What Is Your Risk Tolerance?
Investing retirement savings in your own business offers something many traditional investments can’t: the ability to directly shape the outcome. However, it also increases concentration risk, as a significant portion of your retirement funds may be tied to a single privately owned company.
Ask yourself:
- How much of my retirement savings am I comfortable investing?
- What would happen to my retirement plan if the business underperformed?
- Do I have other retirement savings or investments?
- How much working capital will the business actually need?
- Would using less retirement capital and combining ROBS with another funding source make more sense?
There’s no one-size-fits-all answer. The right amount depends on your financial situation, the opportunity you’re pursuing, your retirement goals, and your tolerance for risk.
3. How Does This Fit Into Your Long-Term Goals?
ROBS is more than a business funding decision. It can also play an important role in your long-term retirement strategy.
Because your retirement plan invests in the business, the value of that investment is tied, in part, to the company’s performance over time.
As you evaluate your options, think beyond the initial funding you need. Consider your long-term business goals, retirement timeline, other savings and investments, and how much financial flexibility you’d like to maintain outside the company.
Before making a significant retirement investment, it may be helpful to consult qualified financial, tax, and legal professionals about your individual circumstances.
Why Entrepreneurs Consider ROBS
For entrepreneurs who have spent years building retirement savings, ROBS offers an alternative to financing an entire business purchase or startup with debt.
When properly structured, ROBS can allow eligible entrepreneurs to invest retirement funds into a business without an early-withdrawal penalty or the monthly principal and interest payments associated with a traditional business loan.
Depending on your situation, ROBS can provide:
- Funding without monthly loan payments
- No interest charges on the amount invested through ROBS
- More working capital available for business needs
- An opportunity to start or purchase a business
- Flexibility to combine retirement funds with other financing strategies
Instead of directing a portion of early revenue toward servicing debt on the ROBS portion of your funding, you may have more flexibility to invest in inventory, equipment, employees, marketing, or other business needs.
You Don’t Have to Fund the Entire Business With ROBS
ROBS doesn’t have to be your sole source of funding. It can work in combination with other financing solutions.
For instance, you might use eligible retirement funds to cover part of the purchase price of a business, while an SBA loan or another funding option helps meet the remaining capital needs.
By combining funding sources, entrepreneurs can gain more flexibility and control over how much of their retirement savings they choose to invest.
Want to learn more about combining ROBS with other financing options? Explore how ROBS can work alongside SBA loans and other funding sources.
So, How Much of Your 401(k) Should You Use for ROBS?
There isn’t a universal number or percentage. The amount you choose should reflect several factors, including:
- The amount of eligible retirement funds available to you
- How much capital the business actually needs
- Your working-capital requirements
- Your other funding options
- Your risk tolerance
- Your retirement timeline and long-term financial goals
The objective isn’t simply to invest the maximum amount available. It’s to create a funding strategy that supports your business’s capital needs while preserving alignment with your long-term financial goals.
The Bottom Line
ROBS can give eligible entrepreneurs considerable flexibility in deciding how much retirement capital to invest in a business. Depending on your retirement accounts and rollover eligibility, you may be able to use a portion of your available funds or significantly more.
But access and strategy are two different questions.
The right amount is the amount that makes sense for your business needs, your available retirement assets, your risk tolerance, and your long-term goals. Understanding those factors before you move forward can help you make a more informed funding decision.
Ready to Find Out How Much You Could Use?
Whether you’re just starting to explore ROBS or you’re ready to move forward, understanding your financing options is an important first step.
Guidant Financial has helped more than 35,000 entrepreneurs pursue their dreams of business ownership.
Our team specializes in helping entrepreneurs understand 401(k) Business Financing and how it may fit alongside other business funding options.
Call us today at 425-289-3200 for a free, no-pressure business consultation to get started or pre-qualify in minutes for business financing.